
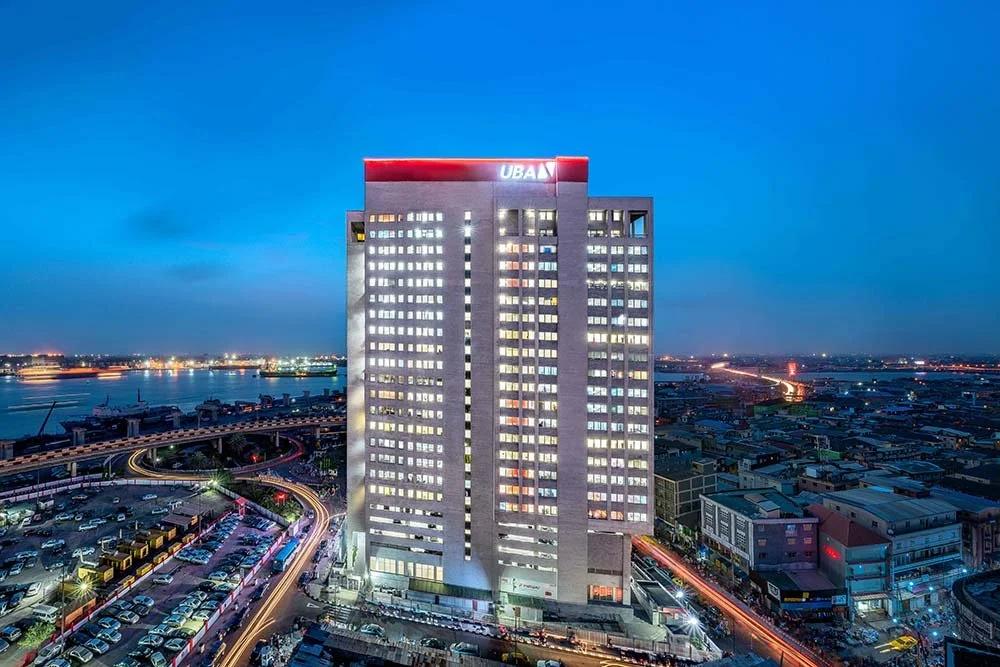
United Bank for Africa Plc (UBA) has been included among the Nigerian banks whose outlooks were revised to Positive from Stable by international rating agency Fitch Ratings.
The action, reported on October 15, follows a similar reassessment of Nigeria’s sovereign outlook and reflects improving expectations for the operating environment and the financial resilience of selected banking institutions.
Fitch maintained the affected institutions’ Long-Term Issuer Default Ratings at ‘B’. The revision therefore signals a more favourable assessment of future credit conditions rather than an immediate upgrade of UBA’s rating.
For UBA, the development comes amid continued attention to the strength of Nigerian banks following the Central Bank of Nigeria’s recapitalisation programme and wider efforts to strengthen the financial system.
UBA has a substantial presence beyond Nigeria, with operations across several African markets and international financial centres. Its geographic reach creates opportunities to support cross-border trade, corporate banking, payments and remittance services.
However, a broad regional footprint also requires careful management of currency movements, country-specific risks, credit exposures and regulatory requirements across different jurisdictions.
The rating outlook is particularly relevant in an environment where investors are examining banks’ ability to maintain capital buffers while expanding lending and supporting economic activity.
Improved macroeconomic conditions could support banking-sector performance through better business confidence, more predictable foreign exchange conditions and stronger repayment capacity among borrowers.
These benefits are not automatic. Banks must continue to manage non-performing loans, operating costs and funding pressures while maintaining adequate provisions against potential credit losses.
UBA’s performance will also depend on its ability to translate regional scale into sustainable earnings and efficient operations. Growth in transaction banking, digital services and corporate finance can create opportunities, but execution and risk management remain essential.
For shareholders, the positive outlook offers an additional signal about the direction of external credit assessments. It should nevertheless be considered alongside UBA’s financial results, capital position, dividend policy and exposure to different markets.
The latest rating action also illustrates the relationship between sovereign risk and bank creditworthiness. When an economy’s external and policy conditions improve, domestic lenders may benefit from a more supportive environment, although individual institutions retain distinct risk profiles.
UBA will therefore need to sustain prudent lending, capital discipline and effective oversight of its international operations to convert the more favourable outlook into stronger long-term financial performance.