
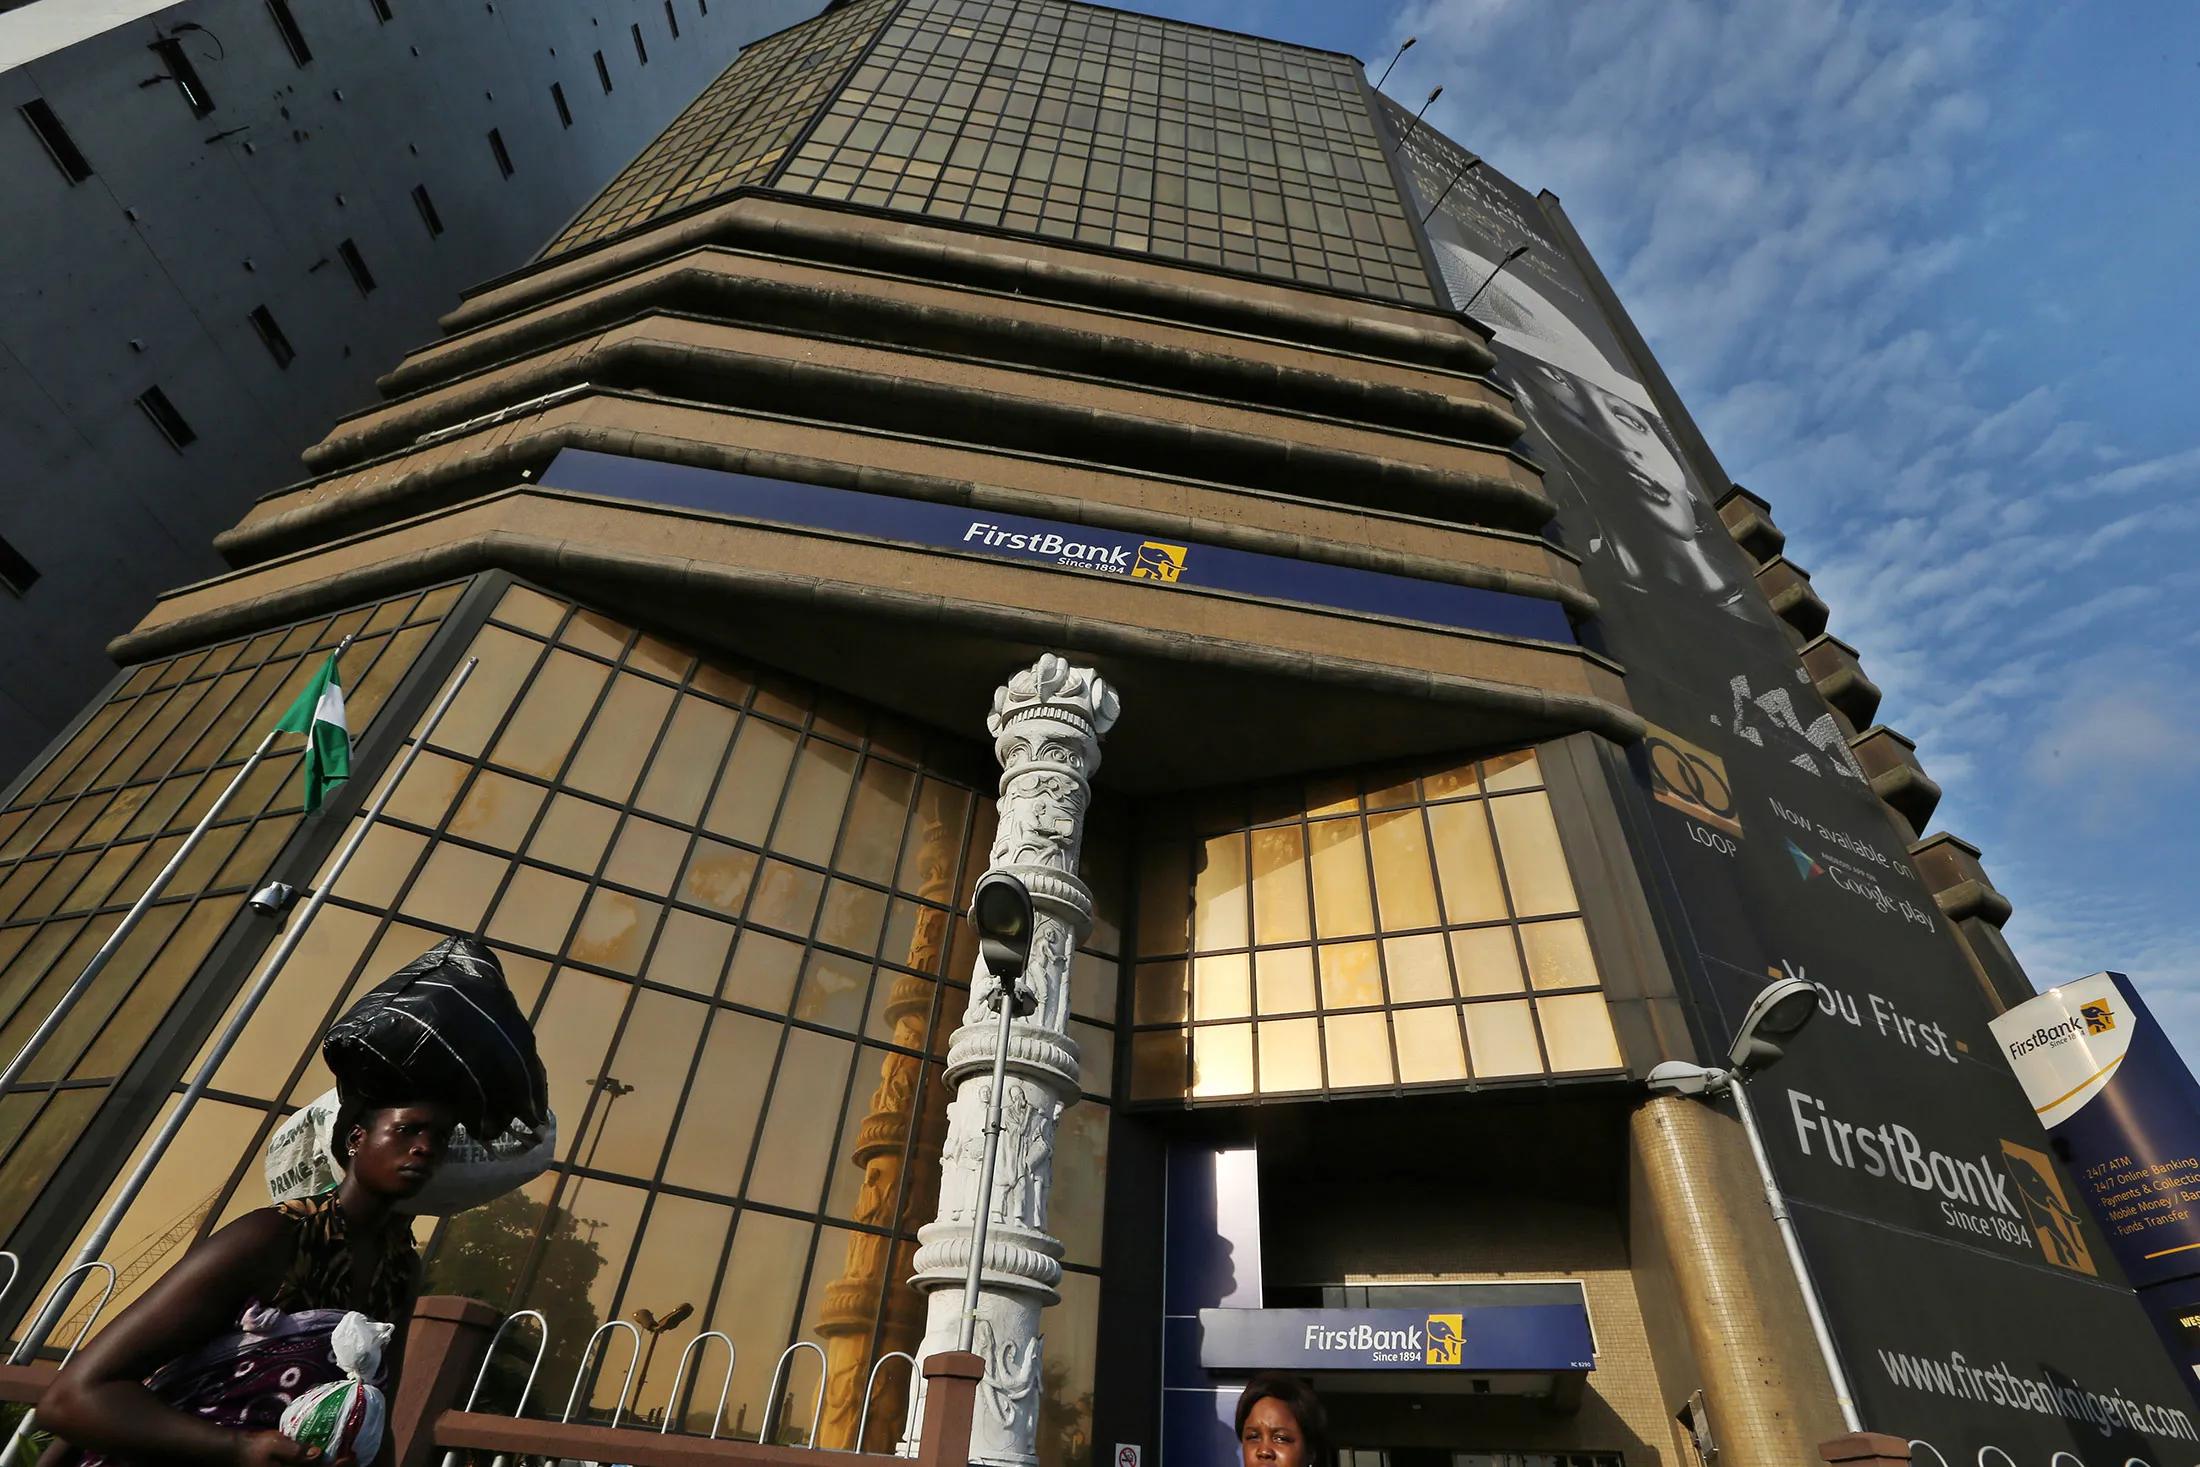
First Bank of Nigeria Limited has received a Positive outlook revision from Fitch Ratings after restoring compliance with its regulatory capital adequacy requirement, although profitability and asset quality remain important considerations for the lender.
Fitch announced the outlook change on October 15 as part of a wider reassessment of nine Nigerian banks and two bank holding companies. The agency affirmed First Bank’s Long-Term Issuer Default Rating at ‘B’.
According to the rating assessment, First Bank’s capital adequacy ratio fell below the applicable minimum requirement of 15 per cent at the end of 2025 following a sharp increase in impaired loans.
The bank subsequently restored compliance, with its capital adequacy ratio rising to 16.7 per cent at the end of June 2026. Fitch attributed the recovery to strong profitability and a relatively small capital raising.
Capital adequacy is an important measure of a bank’s ability to absorb losses relative to the risks attached to its assets. Maintaining an adequate buffer helps support depositor confidence and the lender’s capacity to continue operating during periods of financial stress.
However, a recovery in capital adequacy does not eliminate the need to address impaired loans. Deteriorating asset quality can require additional provisions, reduce earnings and place renewed pressure on capital if losses exceed expectations.
FirstBank’s parent company, First HoldCo Plc, also faces earnings pressures. Published industry figures show that the group’s profit before tax declined by 70.5 per cent in 2025, reflecting the uneven performance of Nigeria’s largest banking groups.
The decline underscores the importance of looking beyond capital ratios when assessing a bank’s financial position. Profitability, credit-loss provisions, liquidity and the quality of earnings all contribute to its overall resilience.
The positive Fitch outlook reflects improved expectations for the operating environment and the bank’s restored capital compliance, rather than a guarantee of immediate earnings growth.
For FirstBank, the next priority will be to maintain adequate capital buffers while improving loan quality and sustaining earnings without taking excessive risks.
Investors will also be watching subsequent disclosures from First HoldCo for evidence that the group can stabilise profitability and manage its balance sheet effectively.
The latest rating assessment places FirstBank’s capital recovery at the centre of the story, while highlighting the importance of turning regulatory compliance into sustainable financial performance.