
Regulator identifies professional standards, digital innovation and stronger governance as priorities for expanding insurance penetration and supporting national development
The National Insurance Commission (NAICOM) has called on insurance brokers to rebuild public confidence in the industry, expand insurance coverage and mobilise long-term investment to support infrastructure development and Nigeria’s economic growth.
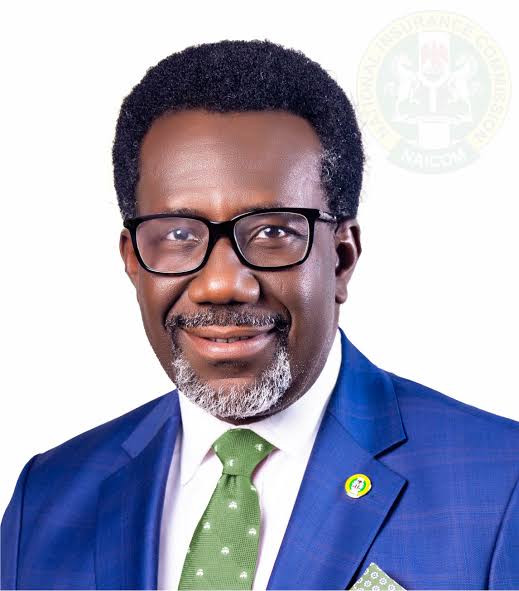
The Commissioner for Insurance and Chief Executive Officer of NAICOM, Mr Olusegun Omosehin, made the call at the 2026 National Insurance Brokers Conference and Exhibition in Abuja, held under the theme, “Insurance: Infrastructure Financing & National Development Agenda.”
Omosehin described insurance brokers as important participants in risk management, consumer protection and investment mobilisation, urging them to uphold higher professional standards and make insurance services more accessible and reliable to Nigerians.
He said the industry must strengthen public confidence if it is to increase penetration and play a more significant role in financing the country’s development priorities.
Insurance provides a mechanism for individuals and businesses to transfer specified financial risks to insurers in exchange for premiums. When effectively managed, the industry can also accumulate funds that support long-term investments, including bonds and other financial instruments.
However, low public confidence, limited awareness and concerns about claims settlement can discourage individuals and businesses from purchasing insurance products.
NIIRA 2025 and industry reforms
The NAICOM chief identified the Nigerian Insurance Industry Reform Act (NIIRA) 2025 as an important framework for strengthening the financial capacity of insurance institutions, improving corporate governance and accountability, and rebuilding confidence in the sector.
The reform agenda places renewed emphasis on the ability of insurers and intermediaries to meet their obligations, operate transparently and maintain appropriate standards.
For insurance brokers, compliance extends beyond meeting regulatory requirements to ensuring that customers receive accurate information about policies, exclusions, premiums and claims procedures.
Brokers also have a responsibility to help customers identify suitable coverage rather than treating insurance solely as a transactional product.
Stronger professional standards could help reduce misunderstandings between policyholders and insurers while improving confidence in the industry.
Digital technology and wider insurance coverage
Omosehin urged brokers to embrace innovation and digital technologies to improve service delivery and comply fully with regulatory requirements.
Digital platforms can make it easier for customers to obtain information, compare products, purchase policies and submit claims. They can also improve record-keeping and communication between brokers, insurers and policyholders.
However, technology must be supported by appropriate data protection, cybersecurity, transparent pricing and accessible complaint-resolution mechanisms.
The regulator also encouraged brokers to establish strategic partnerships with other sectors of the economy to identify new opportunities and expand insurance coverage.
Potential areas of collaboration include infrastructure, construction, agriculture, transportation, manufacturing and small-business development, where appropriate insurance arrangements can help manage operational risks.
Mobilising investment for national development
Insurance companies can contribute to infrastructure financing by investing eligible long-term funds in regulated financial instruments, subject to applicable investment and solvency requirements.
A stronger insurance industry could therefore serve two complementary purposes: providing protection against financial losses and helping mobilise funds for productive investment.
Achieving that objective will require a sustainable balance between investment returns, liquidity, policyholder protection and the ability to settle claims when they fall due.
For NAICOM, the challenge is to ensure that reforms translate into improved consumer experience, greater insurance penetration and a more credible industry.
For brokers, the message is clear: rebuilding trust through professionalism, transparency and reliable service will be central to increasing the sector’s contribution to Nigeria’s economic development.