
Nigerian banks and fintech companies are seeking additional time to comply with the Central Bank of Nigeria’s payment-data localisation requirements as the financial services industry confronts the cost and technical complexity of moving critical digital infrastructure closer to home.
Industry concerns include specialised technology skills, migration costs, cybersecurity and the resilience of Nigeria’s fibre infrastructure.
The CBN’s localisation requirement is expected to affect banks, fintech companies and other payment operators handling Nigerian transaction data, with compliance expected by the end of 2026.
Industry executives have argued that Nigeria possesses sufficient data-centre capacity to accommodate much of the transition, although infrastructure capacity alone may not determine whether migration proceeds smoothly.
₦200bn Technology Spending Under Spotlight
The transition is significant because Nigeria’s biggest financial institutions already spend heavily on cloud and information technology services.
A recent industry assessment estimated that the country’s 10 largest banks spend about ₦200 billion quarterly on cloud and IT services, putting the economics of localisation under greater scrutiny.
Banks increasingly rely on cloud computing and data infrastructure for mobile applications, payment processing, customer databases, fraud detection and other critical operations.
Moving or restructuring some of these workloads can therefore require more than simply transferring information from one server to another.
Financial institutions must ensure systems remain available during migration, comply with security requirements and maintain sufficient disaster-recovery capacity.
Infrastructure Available, But Skills Remain Challenge
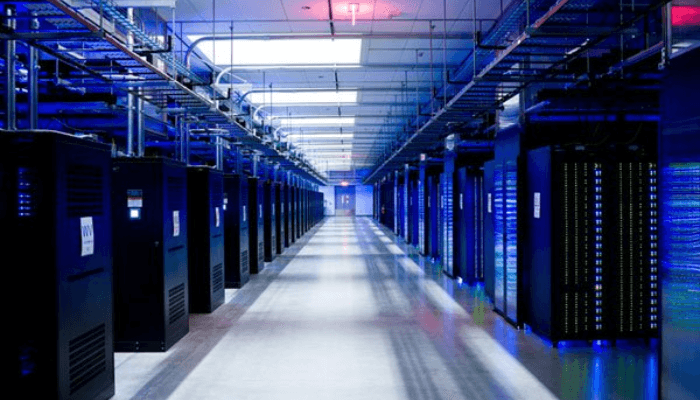
Technology industry representatives have said local data-centre infrastructure has sufficient capacity to support the localisation push.
The bigger challenges could involve access to specialised personnel, pricing and the security of fibre infrastructure connecting data centres to financial institutions and customers.
Those concerns demonstrate why data sovereignty is increasingly becoming a business issue rather than simply a regulatory one.
Localisation could potentially direct more technology spending towards domestic cloud, data-centre and connectivity providers.
But banks and fintech companies will also have to determine whether local infrastructure can provide the performance, redundancy and reliability required for large-scale payment operations.
Digital Sovereignty Meets Financial Stability
The CBN’s wider objective includes strengthening oversight of Nigeria’s rapidly expanding digital payments ecosystem.
Nigeria has produced major fintech businesses and witnessed rapid adoption of digital transactions, but that growth also increases the amount of sensitive financial information moving through technology infrastructure.
Localisation could give regulators greater visibility and jurisdiction over critical payment data.
For technology companies, however, compliance will need to be balanced against operational efficiency.
The transition therefore represents a significant test for Nigeria’s domestic cloud and data-centre industry.
If implemented effectively, it could increase demand for local digital infrastructure. But the concerns raised by financial institutions indicate that adequate capacity must be accompanied by skilled personnel, resilient fibre networks, competitive pricing and strong cybersecurity.