
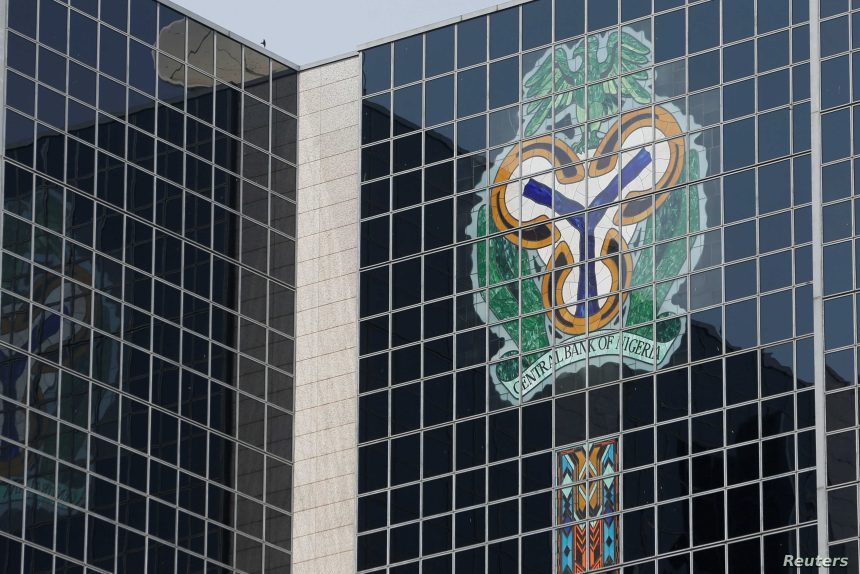
Nigeria’s Central Bank and the Nigerian Communications Commission are working to expand their collaboration on fraud prevention, as regulators seek to reduce the risks associated with recycled telephone numbers and unauthorised access to customers’ financial accounts.
The initiative is expected to extend the use of the Telecommunications Identity Risk Management System (TIRMS) to more sectors where telephone numbers are used to identify customers and facilitate transactions.
The NCC’s Executive Vice-Chairman, Aminu Maida, disclosed the plan at the 95th Telecom Consumer Parliament in Lagos on Tuesday, October 20, according to a report published by The Guardian on Wednesday.
Recycled telephone numbers create security challenges
Telephone numbers have become an important part of the identity and authentication systems used by banks, fintech companies and other digital service providers.
However, mobile numbers may be reassigned to new subscribers after previous owners stop using them. If account records and security controls are not updated appropriately, a recycled number can create risks for customers whose financial or digital accounts remain linked to it.
Fraudsters may also exploit weaknesses in account recovery procedures, identity verification and customer authentication to gain unauthorised access to accounts.
The CBN-NCC collaboration seeks to address part of this problem by improving the identification of telephone numbers associated with fraud and reducing the likelihood that recycled numbers will be misused.
Financial institutions face pressure to strengthen controls
The planned expansion has implications for banks, payment service providers, telecommunications companies and other businesses that use telephone numbers as part of their customer identification processes.
Financial institutions may need to improve the way they verify customers’ contact information, handle changes to registered numbers and respond to suspicious account activity.
The initiative also highlights the importance of coordination between regulators. Banking fraud increasingly involves digital channels, telecommunications infrastructure and identity systems, making cooperation between agencies essential.
Nevertheless, a fraud-risk database is not a substitute for robust identity checks, transaction monitoring, secure authentication and effective customer complaint resolution.
CBN maintains focus on monetary and financial stability
The fraud-prevention initiative comes as the CBN continues to balance monetary policy objectives with its responsibility for financial-system stability.
The apex bank’s official website lists the Monetary Policy Rate at 23 per cent following the Monetary Policy Committee meeting held on September 21 and 22, 2026. It also identifies supervisory attention to terrorism-financing risks among its recent regulatory activities.
The policy rate influences the broader cost of borrowing, while supervisory measures are designed to protect the integrity of the financial system. Both areas remain important to banks, businesses and consumers.
What it means for bank customers
Customers should ensure that their telephone numbers and contact details registered with banks are current. Anyone who changes a number should follow the bank’s official procedure for updating account information.
Customers should also avoid sharing one-time passwords, personal identification numbers and other confidential banking details. Suspicious messages or unauthorised transactions should be reported promptly through verified channels.
The proposed expansion of TIRMS represents another step towards addressing the links between telecommunications identity and financial fraud. Its effectiveness will depend on implementation, the quality of information shared and how quickly institutions act on identified risks.