
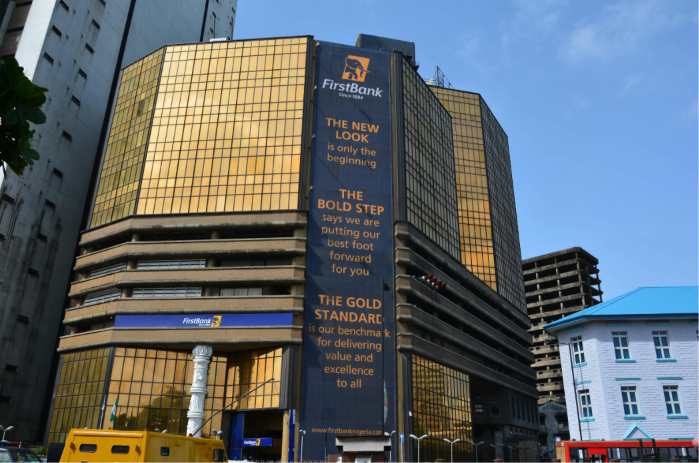
First HoldCo Plc has reported a profit after tax of ₦744.45 billion for the nine months ended September 30, 2026, representing a 65.11 per cent increase compared with the corresponding period of the previous year.
The financial performance highlights the group’s ability to maintain profitability amid changing conditions in Nigeria’s banking and financial services industry.
According to its reported financial results, the holding company recorded a profit before tax of ₦911.24 billion during the nine-month period.
The improvement in profit after tax represents a significant development for the financial services group, which has continued to implement measures aimed at strengthening its operations and improving financial performance.
However, the results also revealed areas that require attention, particularly the movement in net interest income and the performance recorded during the third quarter.
Net interest income declined by 16.02 per cent, indicating that income generated from interest-bearing assets, after accounting for interest expenses, came under pressure during the reporting period.
This development is important because net interest income remains one of the major sources of revenue for commercial banking operations.
Changes in lending rates, deposit costs, loan demand and the composition of interest-earning assets can influence the performance of this income category.
The company’s third-quarter profit before tax also declined by 22.48 per cent compared with the second quarter, suggesting that its earnings momentum moderated towards the end of the reporting period.
Another important aspect of the financial results is the group’s non-performing loan ratio, which stood at 10.40 per cent.
The non-performing loan ratio measures the proportion of a bank’s loan portfolio that is no longer generating repayments according to agreed terms.
A high ratio can create pressure on a financial institution because it may require additional provisions for potential credit losses and reduce the amount of funds available for productive lending.
The reported 10.40 per cent ratio therefore remains an important indicator for investors monitoring the quality of First HoldCo’s loan portfolio.
Investors will also be interested in how the group manages its credit risks while maintaining profitability and supporting business expansion.
For Nigerian banks, the operating environment has remained challenging due to changing monetary conditions, competition for deposits, foreign exchange movements and the need to strengthen capital positions.
First HoldCo’s latest results provide evidence of strong growth in reported nine-month profit, but the decline in net interest income and the weaker third-quarter performance suggest that investors should examine the quality and sustainability of earnings rather than relying on profit growth alone.
The group’s future performance will depend on its ability to maintain revenue generation, manage operating expenses, improve asset quality and strengthen its balance sheet.
The results are expected to remain an important reference point for shareholders and market analysts assessing the company’s financial position and outlook.