
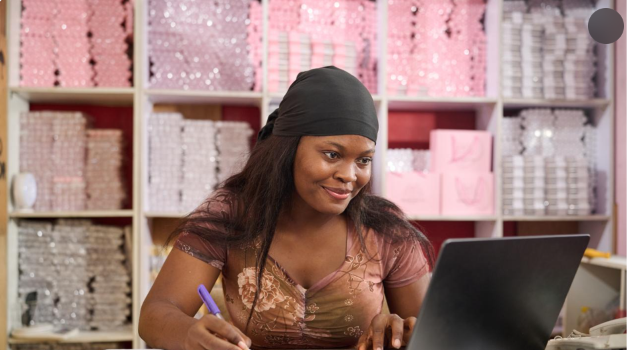
The International Finance Corporation (IFC) has called on financial institutions across Africa to adopt data-driven lending models to improve access to finance for women-owned businesses, particularly small and medium-sized enterprises operating in Nigeria.
The organisation said traditional lending requirements, especially the heavy dependence on physical collateral and personal guarantees, have continued to prevent many women entrepreneurs from accessing the financing required to expand their businesses.
The IFC Africa Regional Lead for Gender Solutions and Impact, Marieme Niang, made the call during an interview with The PUNCH on the sidelines of the Creative Africa Nexus Weekend 2026 in Lagos.
Niang explained that banks and other financial institutions should consider alternative methods of assessing the financial strength of small businesses instead of relying mainly on conventional collateral requirements.
According to her, reliable business records, cash flow information and digital transaction histories can provide useful evidence of a company’s ability to repay borrowed funds.
She noted that many small businesses across Africa operate largely through cash transactions, making it difficult for lenders to obtain sufficient information about their financial performance.
This situation often creates a gap between entrepreneurs seeking financing and financial institutions concerned about lending risks.
Niang argued that digitalising business transactions would help entrepreneurs establish more reliable financial records, making it easier for banks to assess their creditworthiness.
She also encouraged financial institutions to develop financing products that reflect the different needs and growth stages of women-owned businesses.
The IFC official highlighted alternative credit scoring as one of the approaches that could help address the financing challenge.
Under this model, lenders can examine business cash flows, transaction records and other reliable information when determining whether an entrepreneur qualifies for financing.
She also advocated the adoption of the WeFinance Code, an initiative that encourages financial institutions to collect gender-disaggregated data, develop products for women entrepreneurs and improve female representation in leadership positions.
Niang said stronger involvement from central banks could support the implementation of the framework and encourage financial institutions to take measurable steps towards improving access to finance for women.
She explained that women entrepreneurs frequently complain about inadequate financing, while lenders often argue that many businesses are not sufficiently prepared to receive investment.
To address both challenges, the IFC has been supporting entrepreneurs through business coaching, mentorship, technical assistance and connections with potential investors.
One of its initiatives is She Wins Africa, which focuses on supporting women-led businesses across the continent.
According to Niang, the first phase of the programme supported 100 women entrepreneurs across 23 African countries and mobilised more than $4 million.
The beneficiaries operated in different sectors, including healthcare, agribusiness, tourism, technology and creative industries.
The programme provided selected businesses with catalytic grants designed to help them attract additional investment.
The IFC is also developing the second phase, known as She Wins Africa Academy, which aims to support 1,000 women-led businesses through peer learning, business development and other support services.
Niang advised entrepreneurs to seek financing that matches their business development stages.
She explained that smaller businesses could begin with fintech companies and microfinance institutions before approaching commercial banks and investment funds as their operations expand.
Another important initiative highlighted during the interview is Sourcing2Equal, which the IFC is designing for Nigeria.
The programme aims to connect women-owned businesses with major corporate buyers, creating opportunities for smaller enterprises to participate in larger supply chains.
The initiative has already been implemented in Kenya, where it supported 345 enterprises from a pool of 1,122 women entrepreneurs.
The Kenyan experience also highlighted the financing difficulties businesses can encounter after securing contracts, particularly when they lack sufficient working capital to fulfil large orders.
The IFC is therefore working to address not only access to customers but also the financing required to deliver corporate contracts.
For Nigeria, improved financing opportunities could help women-owned businesses expand production, create employment and contribute more significantly to economic growth.
However, achieving these objectives will require cooperation between financial institutions, regulators, development organisations and business owners.
The IFC’s recommendations highlight the importance of combining financial inclusion with digital innovation, business development and stronger access to commercial opportunities.Punch Newspapers