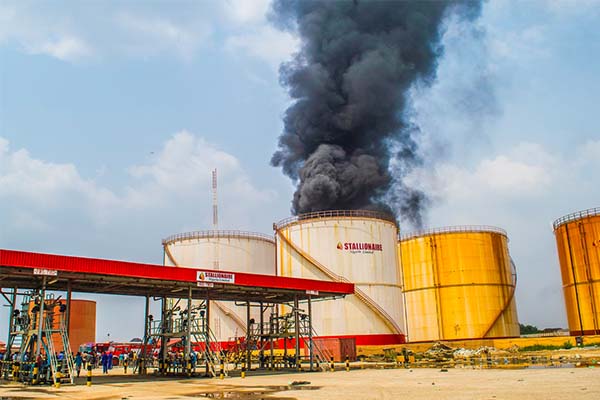


United Bank for Africa Plc (UBA) has secured a favourable ruling in its ₦156 billion debt recovery dispute with Stallion Group and related companies.
The Federal High Court in Lagos delivered judgment on Friday, October 16, 2026, granting the bank the reliefs it sought and upholding the appointment of a receiver-manager, according to a report by Premium Times.
Justice Daniel Osiagor also affirmed the court’s jurisdiction to hear the case.
The decision marks a significant development in UBA’s effort to recover the outstanding debt.
Court upholds receiver-manager appointment
The court upheld the appointment of Romeo Ese as receiver-manager.
The role involves taking steps permitted by the relevant legal and security arrangements to protect and realise assets for the purpose of debt recovery.
The court also granted reliefs sought by UBA in relation to the dispute.
The ruling strengthens the bank’s legal position. However, the final amount recovered will depend on the implementation of the orders and the assets or receivables available for recovery.
Why debt recovery matters to banks
Banks lend money to businesses and individuals with the expectation that borrowers will repay according to agreed terms.
When a borrower defaults, lenders may seek to recover outstanding amounts through negotiated settlements, enforcement of security or court proceedings.
The process can become more complicated when multiple companies, secured assets or competing claims are involved.
For banks, effective recovery mechanisms help limit losses and support the management of credit risk.
For the wider financial system, predictable enforcement of valid agreements can encourage lending by giving lenders greater confidence that contractual obligations can be enforced.
What happens next?
The ruling gives UBA a stronger legal basis to pursue recovery under the court’s orders.
However, a favourable judgment does not necessarily mean that the entire amount will be recovered immediately. The timing and value of any recovery will depend on the assets available, the enforcement process and any further legal developments.
The report did not include a response from Stallion Group or its representatives. Their position should be sought for a fuller account of the dispute.
The case highlights the importance of robust credit assessment, clear loan documentation and enforceable security arrangements in commercial banking.