
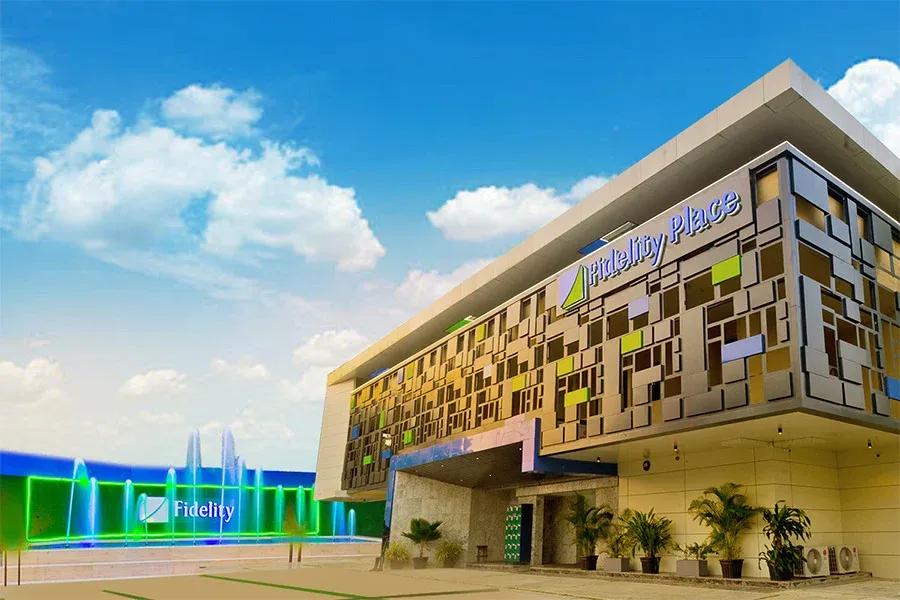
Fitch Ratings has revised the outlook on Fidelity Bank Plc to Positive from Stable, reflecting improving expectations for Nigeria’s operating environment and the potential implications for the bank’s credit profile.
The rating agency announced the change on October 15 alongside similar outlook revisions for other Nigerian banks and financial holding companies. Fidelity Bank’s Long-Term Issuer Default Rating was affirmed at ‘B’.
The development followed Fitch’s decision to revise Nigeria’s sovereign outlook to Positive, reflecting its assessment of ongoing economic reforms and the prospects for a more supportive policy environment.
The rating outlook is significant for Fidelity Bank as Nigeria’s lenders continue to adjust to changes in regulatory capital requirements, funding conditions and the competitive landscape for financial services.
The banking sector’s recapitalisation programme has placed greater emphasis on capital strength and the ability of institutions to support larger financing requirements. However, adequate capital must be accompanied by sound lending practices and effective controls over credit risk.
For Fidelity Bank, the wider environment presents opportunities to expand lending, deepen digital banking services and support businesses seeking financing. At the same time, rising operating costs, borrower repayment pressures and changes in interest rates can influence the quality of earnings.
The positive outlook should therefore be understood as an improvement in Fitch’s assessment of future credit conditions, not as an immediate rating upgrade or a guarantee of higher profitability.
The broader banking sector’s recent earnings figures demonstrate why this distinction matters. Although five major Nigerian banking groups generated combined gross earnings of approximately ₦18.4 trillion in 2025, profitability varied considerably between institutions.
Revenue growth does not necessarily translate into stronger profits when banks face higher impairment charges, operating expenses and other financial pressures.
For Fidelity Bank, sustained performance will depend on its ability to maintain sufficient capital, control non-performing loans, manage funding costs and generate earnings from its lending and service activities.
The bank’s ability to comply with regulatory requirements while expanding its customer base will also be important as competition intensifies across digital and traditional banking channels.
For investors, the revised outlook offers a more favourable external assessment but should be considered alongside published financial results, capital adequacy disclosures and the bank’s risk profile.
The coming reporting periods will provide further evidence of whether the improved operating environment is translating into stronger earnings and more resilient balance-sheet performance.